
Purpose
The stated need is to buy or refinance business equipment.
Amounts, terms and timelines are typical ranges for complete files, subject to underwriting and lender approval.
Compare all programsEducational content only, not a commitment to lend, and not tax, legal or accounting advice.
Browse the AcademyA good equipment file starts with a real purchase, a credible seller, and a payment the business can support. Qualified Commercial reviews all three together instead of treating the quote as the whole story.
Final amount, term, pricing, down payment, and structure depend on the equipment, seller, business cash flow, credit, documentation, and lender approval.
These are preliminary matching points, not an automatic approval. When a fact is missing, the file should ask for it and show More information needed rather than reject the request.
The stated need is to buy or refinance business equipment.
The business has at least one year of operating history.
Annual revenue is at least $100,000.
Estimated personal credit is 640 or higher.
Current operations show positive cash flow before the proposed payment.
The requested amount falls within the $25,000 to $2 million range.
If one of these facts is unknown, we ask for the missing information. A blank field is not a zero and it is not a decline.
The equipment has to be identifiable, used for the business, and appropriate for the proposed term. Common requests include:
Machinery, fabrication tools, lifts, compressors, and systems used to make or service a product.
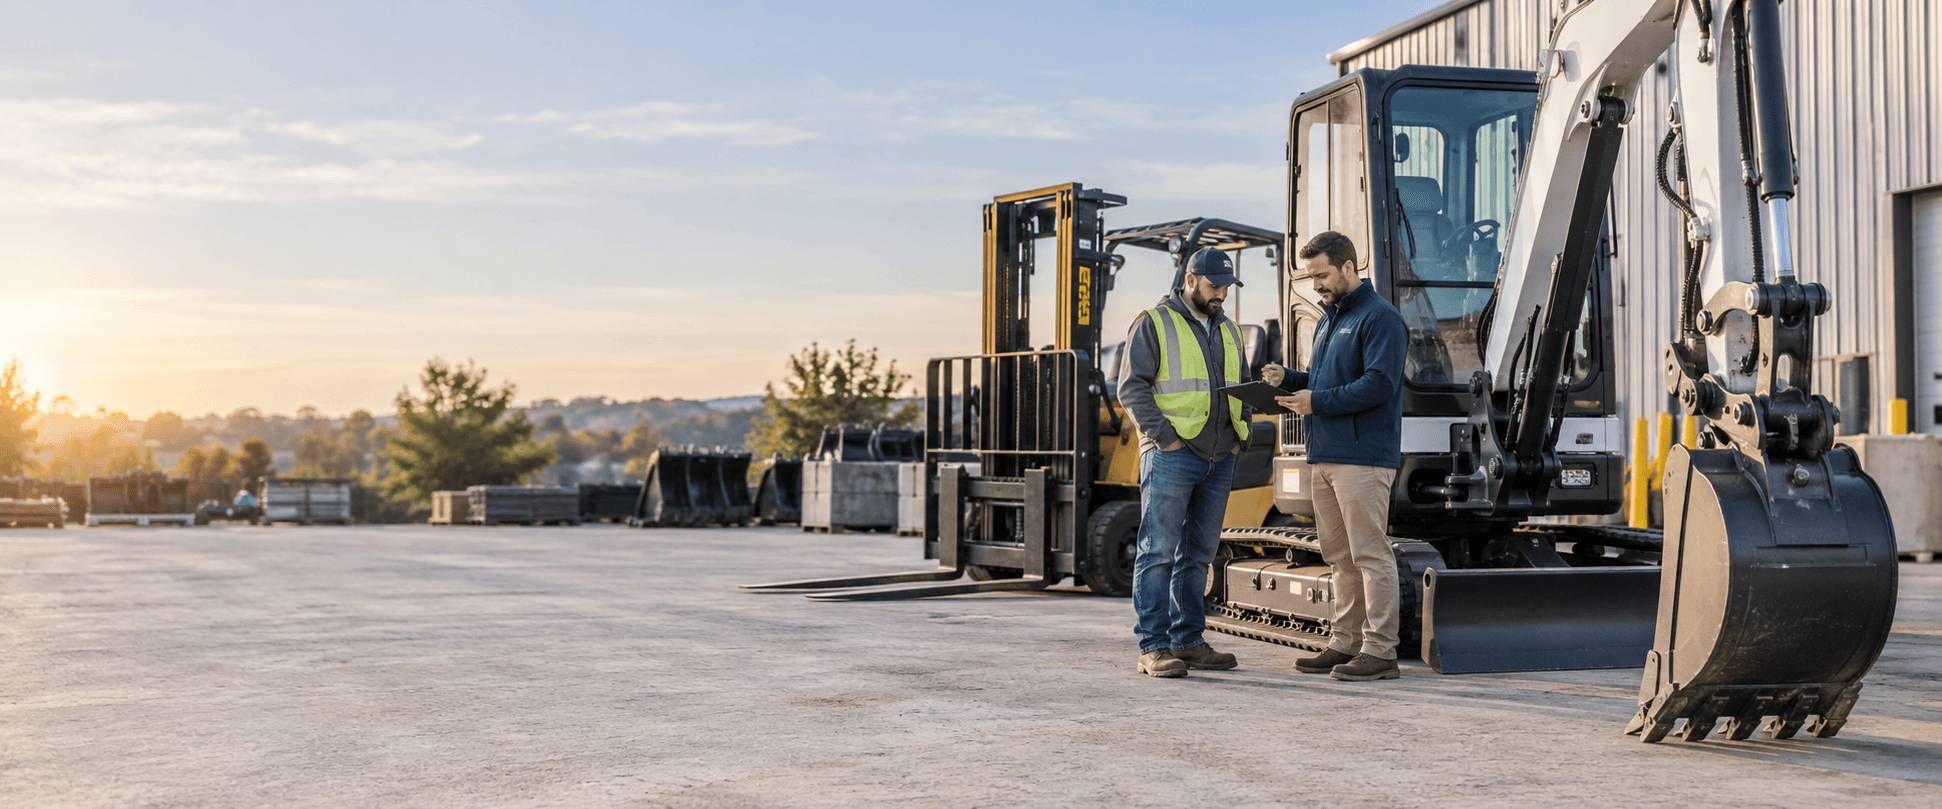
Excavators, loaders, forklifts, compact equipment, and other jobsite assets.
Titled vehicles used in the business. Fleet and transportation requests may be routed to a more specialized program.
Kitchen systems, refrigeration, point-of-sale hardware, fixtures, and essential operating equipment.
Practice equipment, imaging or diagnostic systems, and specialized office assets.
Production technology, servers, automation systems, and other durable business-use hardware.
| What we collect | Why it matters |
|---|---|
| Vendor quote or purchase invoice | Confirms the asset, price, seller, delivery terms, and what is included. |
| Description and serial or model details | Lets underwriting identify and value the actual equipment rather than a broad category. |
| Age and condition | Used equipment can be considered, but age and condition affect useful life, collateral value, and term. |
| Expected useful life | The financing should not outlast an asset that will need replacement first. |
| Seller details | The seller and payment instructions must be verified before closing. |
| Delivery timing | A realistic delivery date keeps approval, insurance, and funding instructions aligned. |
| Intended business use | Underwriting needs to understand how the equipment supports revenue, capacity, or operating efficiency. |
A new asset usually has clearer value support, warranty coverage, and a longer remaining useful life. Underwriting still tests the payment against the business.
Used assets can work when the seller, condition, valuation, and remaining useful life are documented. Older equipment may support a shorter term or require more equity.
A loan is often the cleaner fit when the business expects to own the asset for most of its useful life. The lender generally takes a lien on the equipment.
A lease can make sense when replacement cycles, end-of-term options, or accounting treatment matter. Compare total obligations and buyout terms, not only the monthly payment.
You enter the amount, business use, and quote details. The program and equipment purpose stay attached to the file.
The system checks the published range and asks for any missing business, credit, cash-flow, or equipment facts.
The underwriting team reviews statements and financials, then ties the proposed payment back to the business's actual performance.
If the request fits, final terms, insurance, lien requirements, seller verification, and funding instructions are confirmed before closing.
Yes, used equipment can be considered. Underwriting will review age, condition, seller, value, and remaining useful life before setting a term.
No. It is part of the preliminary matching baseline. Cash flow, existing debt, the equipment, the seller, and the complete credit profile still matter.
You can begin the file, but the quote or invoice is needed to confirm the asset, seller, purchase price, and final structure.
Yes. A request outside the published range of $25,000 to $2 million will be routed for a custom review or to another suitable program instead of being presented as eligible.
Often it does. The exact lien position and any additional support are set by the final lender and structure.
Timing depends on a complete file, equipment and seller verification, insurance, final approval, and closing conditions. We do not promise a same-day close.
The application opens with Equipment Financing and the equipment funding purpose attached, so the review starts in the right place.